01
The Operational Breakdown
- 01
Speed Versus Regulatory Control: Email moves too slowly for fast-moving retail counters, driving tellers and managers toward consumer chat apps that violate banking governance.
- 02
Conflicting Information at Counter and Phone: Branches and central telephone support receive fee or rate adjustments at different times, giving customers conflicting answers.
- 03
Blurred Departmental Boundaries: Discussions involving retail banking, treasury, risk, and human resources mix in unmonitored channels never designed to host them.
- 04
Information Leakage: Confidential internal memos, rates, and operational updates get screenshotted and shared outside the institution.
02
How Tawasol Solves It
Scroll the table to read all columns
| Operational Problem | What Tawasol Does | The Functional Result |
|---|
| Speed Versus Control | Shawts and role-restricted group messaging inside a bank-owned app, backed by instant mobile push notifications. | Branch coordination remains rapid while moving inside a fully governed, compliant boundary. |
|---|
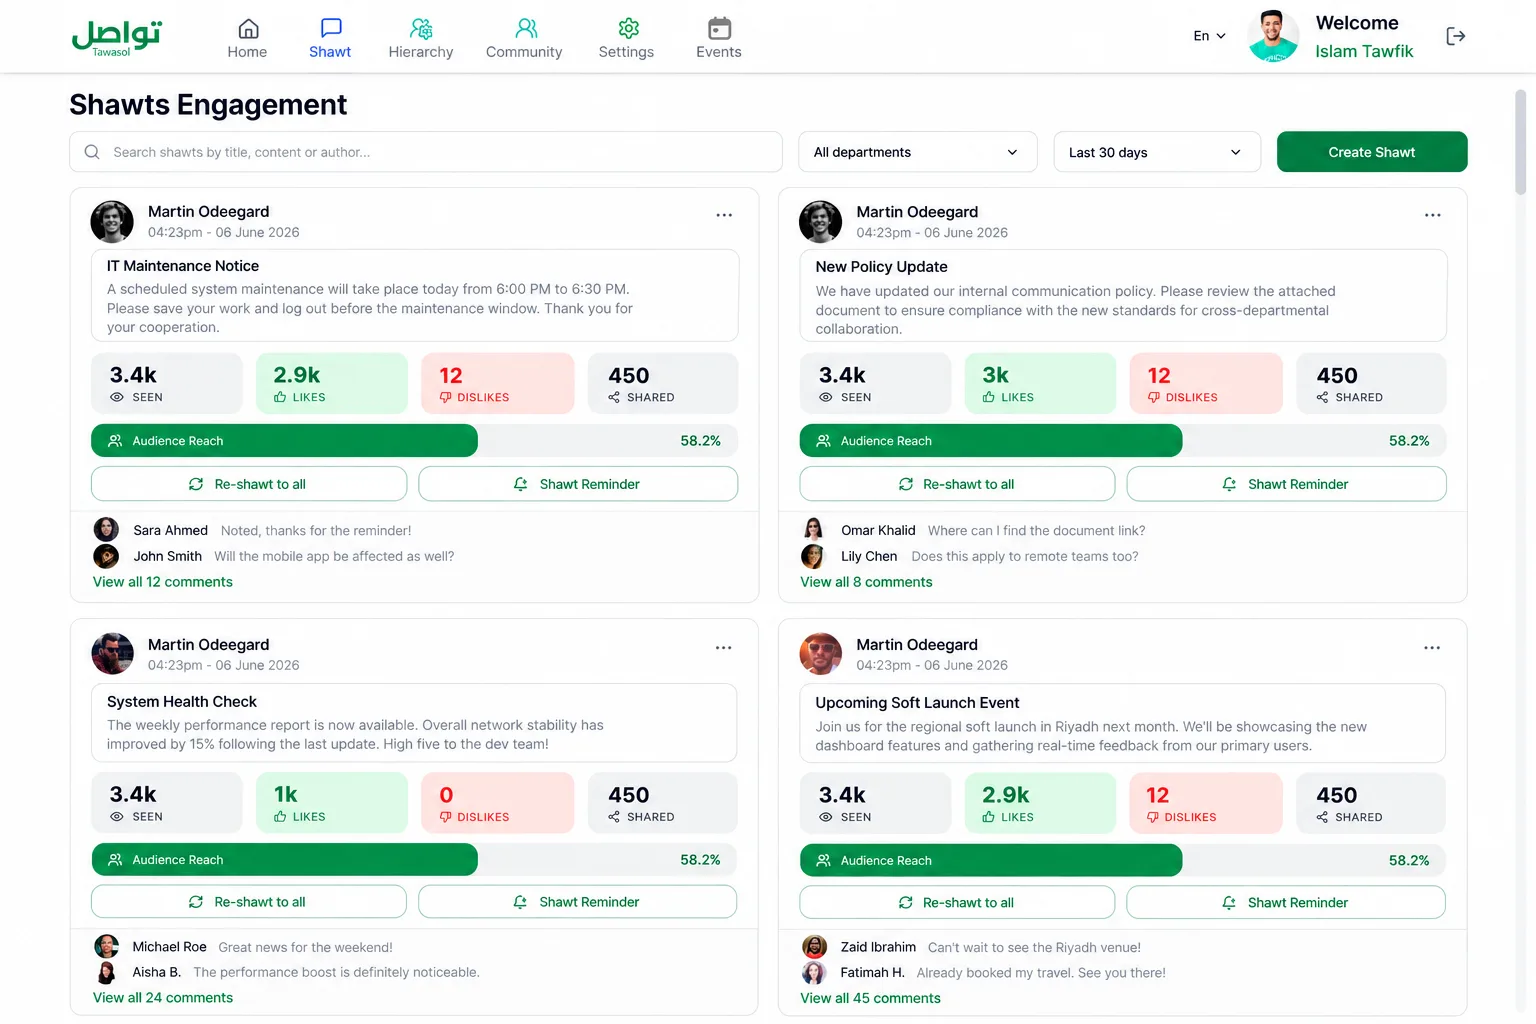
| Conflicting Information | A single Shawt broadcasts simultaneously to the entire branch network and call center, carrying the official policy document from the Library. | Both branch tellers and phone agents operate from the exact same version at the exact same moment. |
|---|
| Blurred Boundaries | Units map to the bank’s organizational hierarchy, applying role-based access rules to every profile. | Treasury, risk, and branch staff only access content relevant to their specific functions. |
|---|
| Information Leakage | Complete prevention of mobile screenshots and screen captures, dynamic watermarking with viewer identity, file download limits, and end-to-end encryption. | Sensitive banking memos remain contained, and any attempt to photograph a screen carries permanent, traceable metadata. |
|---|
03
Case Studies in Practice
01↗
Scenario A: Branch-Wide Regulatory Change
- The Role
- Head of Regulatory Compliance.
- The Situation
- A central bank mandate requires an immediate adjustment to retail account-opening checks across the entire retail network.
- The Action
- She uploads the revised SOP into the Library as a view-only file and issues a Shawt targeting retail branches and branch managers.
- The Outcome
- Branch staff review the requirements before doors open. Clarifications are asked and answered in the comments under the Shawt, providing a single public answer for the whole network. The circular and complete distribution timestamps remain logged for the next audit.
02↗
Scenario B: Counter-Fraud Rapid Alert
- The Role
- Fraud Operations Lead.
- The Situation
- A sophisticated check-forgery ring targets counters across a single metropolitan district.
- The Action
- He issues an urgent Shawt with high-resolution imagery of the counterfeit instrument, targeting solely that district’s branch units and the telephone fraud squad.
- The Outcome
- Tellers receive the alert immediately. When a suspect check appears at a counter, staff post details into the fraud unit's secure group chat, escalating the incident to central investigators in seconds without passing through layers of branch management.
04
Comprehensive Sector Capabilities
- 01
Coordinated Rate Adjustments: Push updated lending tables, deposit rates, and foreign exchange sheets simultaneously to branch tellers and customer support desks.
- 02
Counter-Ready Reference Manuals: Keep operating manuals, compliance checklists, and account forms in the mobile Library for instant reference during live client interactions.
- 03
Bulk Branch Onboarding: Import entire batches of newly licensed personnel from Excel templates directly into branch units, instantly inheriting correct circulars and manuals.
- 04
Mandatory Compliance Cycles: Publish mandatory regulatory seminars under Events; employees register inside the app, and compliance officers confirm attendance records.
- 05
Direct Helpdesk Routing: Staff direct operational questions through Ticketing straight to the responsible desk (e.g., cash handling, IT support, facilities) rather than emailing general distribution lists.
05
Measurable Value
- ↗
Day-to-day: Retail branches and telephone agents act on identical instructions the morning they are issued, keeping staff communication off consumer chat apps.
- ↗
Over time: Communication risk moves into an audited environment, establishing a permanent institutional record that simplifies regulatory examination.
06
Frequently Asked Questions
Can Tawasol run within the bank’s existing data center?
Yes. The platform operates on-premise within your own infrastructure, satisfying central bank data residency mandates.
How does Tawasol stop internal financial memos from leaking?
The system disables screenshots and screen recording, stamps dynamic watermarks (including employee identifier, IP, and timestamp) over files, and restricts documents to view-only.
Can retail staff be blocked from accessing risk or treasury discussions?
Yes. Granular permissions tied to user profiles ensure retail tellers never see communications intended for risk, compliance, or treasury teams.
Does Tawasol integrate with Active Directory?
Yes. User profiles, departmental assignments, and administrative privileges sync centrally with Active Directory.
How quickly can staff at a newly acquired branch be onboarded?
New personnel can be uploaded in bulk via formatted Excel sheets directly into their branch unit, giving them immediate access to relevant documentation.